From HUD
What's moving at HUD HQ and in the field offices we work with.
Floodplain: the FFRMS rescission
This is important information if your project is in or near a floodplain or has wetlands on or adjacent.
On July 10, HUD published a proposed rule aiming to rescind most of the new Federal Flood Risk Management Standard (FFRMS) that was built into HUD's floodplain determinations back in April 2024. The goal of this is to restore the old process for determining the regulatory floodplain. The proposed rule pulls the FFRMS rules out and realigns HUD with FEMA (Federal Emergency Management Agency) and NFIP (National Flood Insurance Program) standards. For projects with floodplain issues, this means the requirements would be less stringent again. We both submitted formal comments to HUD supporting the rescission of FFRMS as they were overbearing and took entire geographic areas off the table. But know that this isn't removing all HUD floodplain rules, just the new FFRMS standards that came out in 2024.
Noise approvals move out of HUD's Office of Community Planning and Development
For years HUD has had a rule that precluded building with the HUD program in places where highway and train noise was above a certain level, or required mitigation. Here are the revisions.
On June 12, HUD published a direct final rule (91 FR 35624) revising its excess noise approval process. Approval authority for projects in unacceptable noise zones now sits with the HUD program office working the project instead of with the Office of Community Planning and Development (CPD).
Under the prior system, CPD had to approve noise attenuation measures and any waiver for projects in unacceptable noise zones — even where CPD had no familiarity with the larger context of the deal. This added many days' worth of delay since a project had to wait in CPD's queue for final approval. For a 221(d)(4) in an unacceptable noise zone, that delay has thankfully been removed.
Together with the improvement to the noise-sensitive outdoor use definitions in Mortgagee Letter 2026-04, which we covered last quarter, HUD has made two significant improvements to noise issues within two quarters.
The ROAD Act became law
If you are building or acquiring single-family build-to-rent developments that you'd like to hold long-term, this is something to pay attention to.
Following up on last quarter's newsletter, the 21st Century ROAD to Housing Act became law on July 11 without being signed by the President, after the ten-day constitutional window expired. The build-to-rent (BTR) exception survived in the new act, so BTR properties aren't subject to the seven-year forced-sale requirement as originally proposed. This means that we are expecting HUD to continue work on their mortgagee letter regulating their underwriting of BTR projects within the HUD financing programs.
The Market
Rates and what we're seeing in the pipeline.
…woof
As everyone in real estate knows, the 10-year closed Q3 at 5.279%, up an incredible 81 bps from the end of Q2. It crossed 5% in September for the first time since 2007. The drivers have become broader than the Middle East story we wrote about last quarter: mainly that inflation is still running above target, oil is back above $100 with supply risk unresolved, and heavy Treasury and corporate issuance is competing for the same investor capital.
On the actual property operating side, the Q3 summer leasing season was less impressive than we expected. Boise was an outlier with real rent growth, however, many other markets only improved marginally over their winter numbers. Concessions are still present in several markets rather than burning off, and vacancy hasn't settled into the 5% range owners were anticipating. This means that the NOI hasn't done much (if anything) to offset the 81 bp rise in treasuries.
With interest rates rising and NOI growth being somewhat stagnant, borrowers have been turning to interest rate buydowns. GNMA investors have developed a real marketplace for buydowns as the borrower appetite for them has increased over Q3. The mechanic of a rate buydown works because most of these loans are DSCR constrained – meaning the interest rate determines what the 1.15x DSCR constrained mortgage will be. A lower rate increases the mortgage amount, meaning that the buydown can be paid out of the incremental proceeds the lower rate creates. At current pricing, those incremental proceeds exceed the fee – meaning that a buydown is sometimes making a “cash-in” refinance get to cash-neutral or cash out. If you have a refinance on the border of cash-out or cash-in, call us and we'll size it both ways.
What We're Watching
A few things we're keeping an eye on this quarter.
Mortgagee letters in drafting
These are letters that HUD drafts for lenders to let us know what they are changing from a regulatory perspective. Since January 2025, these changes have been favorable and eased burdens on borrowers who are obtaining debt through HUD.
HUD has a number of Mortgagee Letters in drafting or clearance, including ones addressing build-to-rent (BTR), 241(a) processing (supplemental construction loans for existing HUD properties), replacement reserves and the PCNA (Project Capital Needs Assessment) structure, large borrower credit requirements, and streamlining the closing process. The BTR letter appears to be furthest along, after it was revived with the ROAD Act resolving the question that had paused HUD's work there (as mentioned above).
The broader MAP efficiency package mortgagee letter we mentioned last quarter (221(d)(4) working capital, cash-out holdbacks tied to repair escrows, and streamlined application checklists) went to OMB and came back on September 8 with a substantial volume of comments. That one looks like it will not be released for a while still (guessing Q2 or Q3 of 2027).
While we have ideas and hints on what they are changing, none of them are published yet and we will cover them as they get published.
Fair Housing Act design and construction: the limitations period
If you own or are acquiring a property built after March 1991, this could affect your exposure on accessibility claims.
On August 13, HUD and DOJ rescinded Question 59 of the 2013 Joint Statement on Fair Housing Act design and construction requirements, which addressed the “continuing violation” theory of Fair Housing violations. Then on August 31, HUD's Office of Fair Housing and Equal Opportunity released a memo adopting a one-year statute of limitations for administrative complaints alleging design and construction violations, effective immediately. This makes the statute of limitations begin when the initial certificate of occupancy was issued, not indefinitely for as long as the condition exists.
What this means for the HUD/FHA lending platform (or even Fair Housing Act claims in general) is still unclear. HUD will need to publish a mortgagee letter before anything is changed for us operationally and many accessibility experts are expecting legal challenges. We will update you as we learn more about how this affects HUD/FHA loan compliance.
Worth reading on where we are in the cycle
Wim found a great article over the summer written by Sam Lawhead at Housing + Markets, “The Apartment Trade Is Over. Back to Apartment Investing.” While it's a long read, we think it was a great explanation of why the multifamily market seems stuck.
Lawhead's argument is that apartment returns from roughly 2010 to 2022 relied on four tailwinds that all happened at once.
- Cap rates compressing under a flood of credit.
- Millennials hitting peak renting years.
- A decade of underbuilding prior to this time.
- A political environment that made aggressive rent growth possible.
All four tailwinds have since reversed. He also argues that the cap rate compression tailwind was driven more by the quantity of credit in the system than by the price of it, which implies that a lowering of interest rates won't necessarily lower cap rates again.
His longer thesis is that historically, the majority of total return in housing came from rental income rather than appreciation. The appreciation-led decade we had from 2010-2022 was an outlier and shouldn't be relied on moving forward – even if treasuries drop. He thus argues for a more traditional real estate play: longer holds and underwriting cashflow as the main business plan.
While that type of real estate might not be super sexy, it is how HUD debt is structured. A 35-year fully amortizing fixed-rate non-recourse loan was never the right instrument for a business model that is all about a five-year cap rate arbitrage.
From the Pipeline
Current activity at Centennial.
The 221(d)(4) new construction transactions we mentioned last quarter are in processing and we're close to submitting a 223(f) refinance in Montana, where the property tax classification change we wrote about earlier this year is positively impacting the underwriting.
Beyond that, a few more 223(f) refinances look likely to start soon in Arizona, Montana, and Idaho.
From Us
What we've published and a personal note.
Published this quarter
Six new pieces went up this quarter: survey requirements, HUD cash flow distribution rules, how a DSCR-constrained loan actually sizes, vacancy rates, program eligibility, and Mortgage Insurance Premium. That brings the library to twenty-two white papers and deal highlights, covering the major HUD multifamily programs and the specific mechanics that tend to decide deals. The full library is at roachlorenz.com/resources.
Where we've been
Both Wim and Brian are members of the Western Mortgagee Advisory Council (WMAC) and attended a conference in Denver, CO in early September. This was a great opportunity to meet with the Denver HUD staff (the office where many of our deals are processed), see the third-party vendors, and catch up with our underwriting network. We are lucky to be working so much with the Western HUD staff – over the past several years especially, HUD's Western region has proven to be a model for other regions on how to work best in these challenging times to creatively move around obstacles and headwinds to help clients provide much needed housing in markets across the western United States.
On a personal note
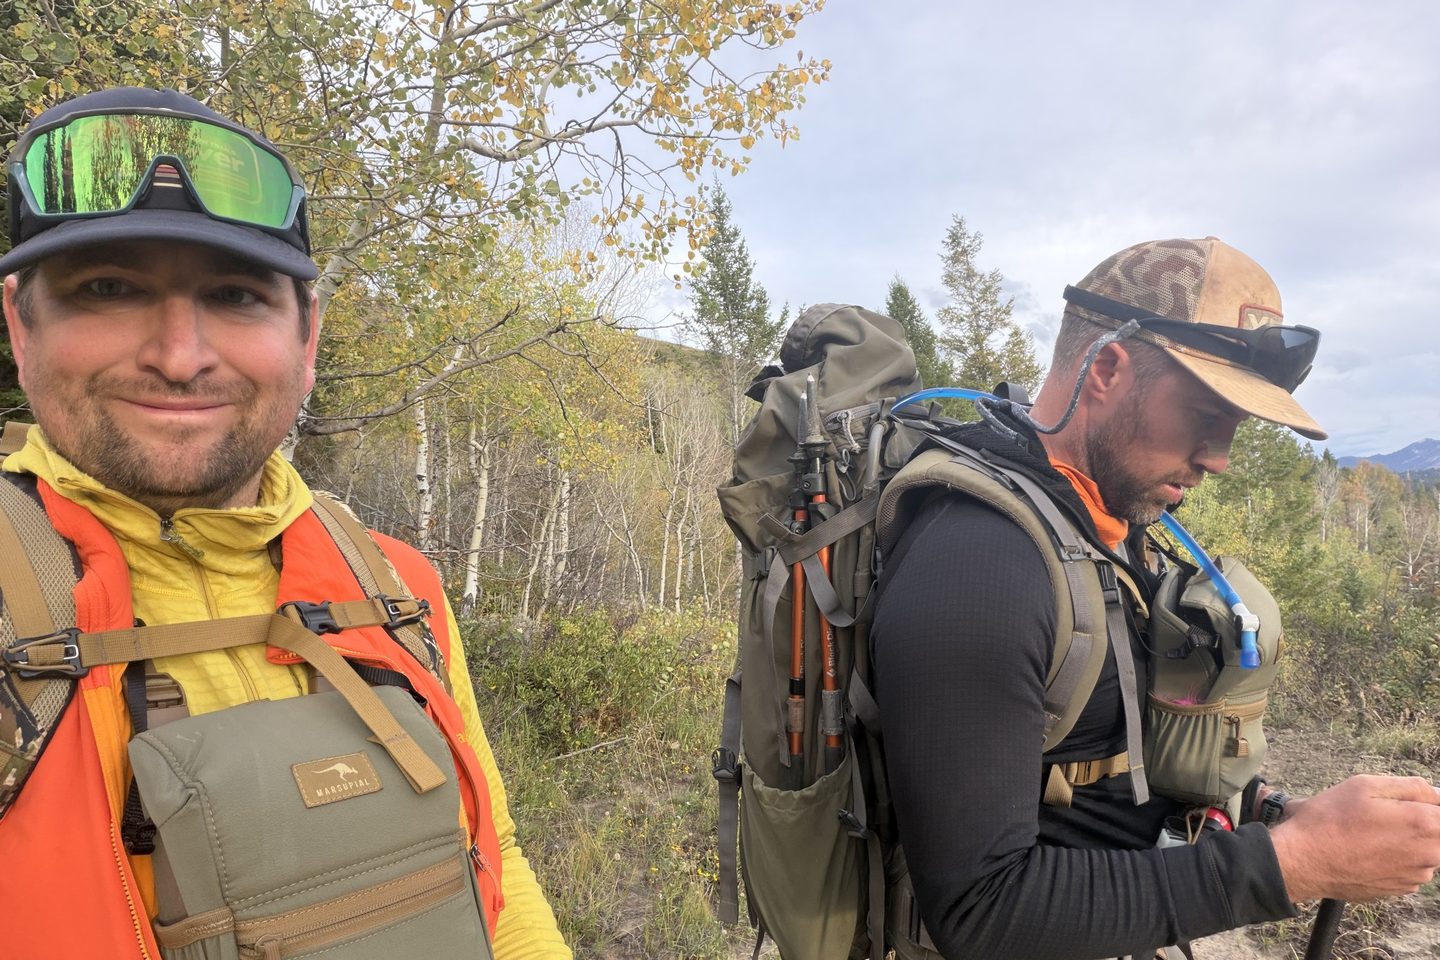
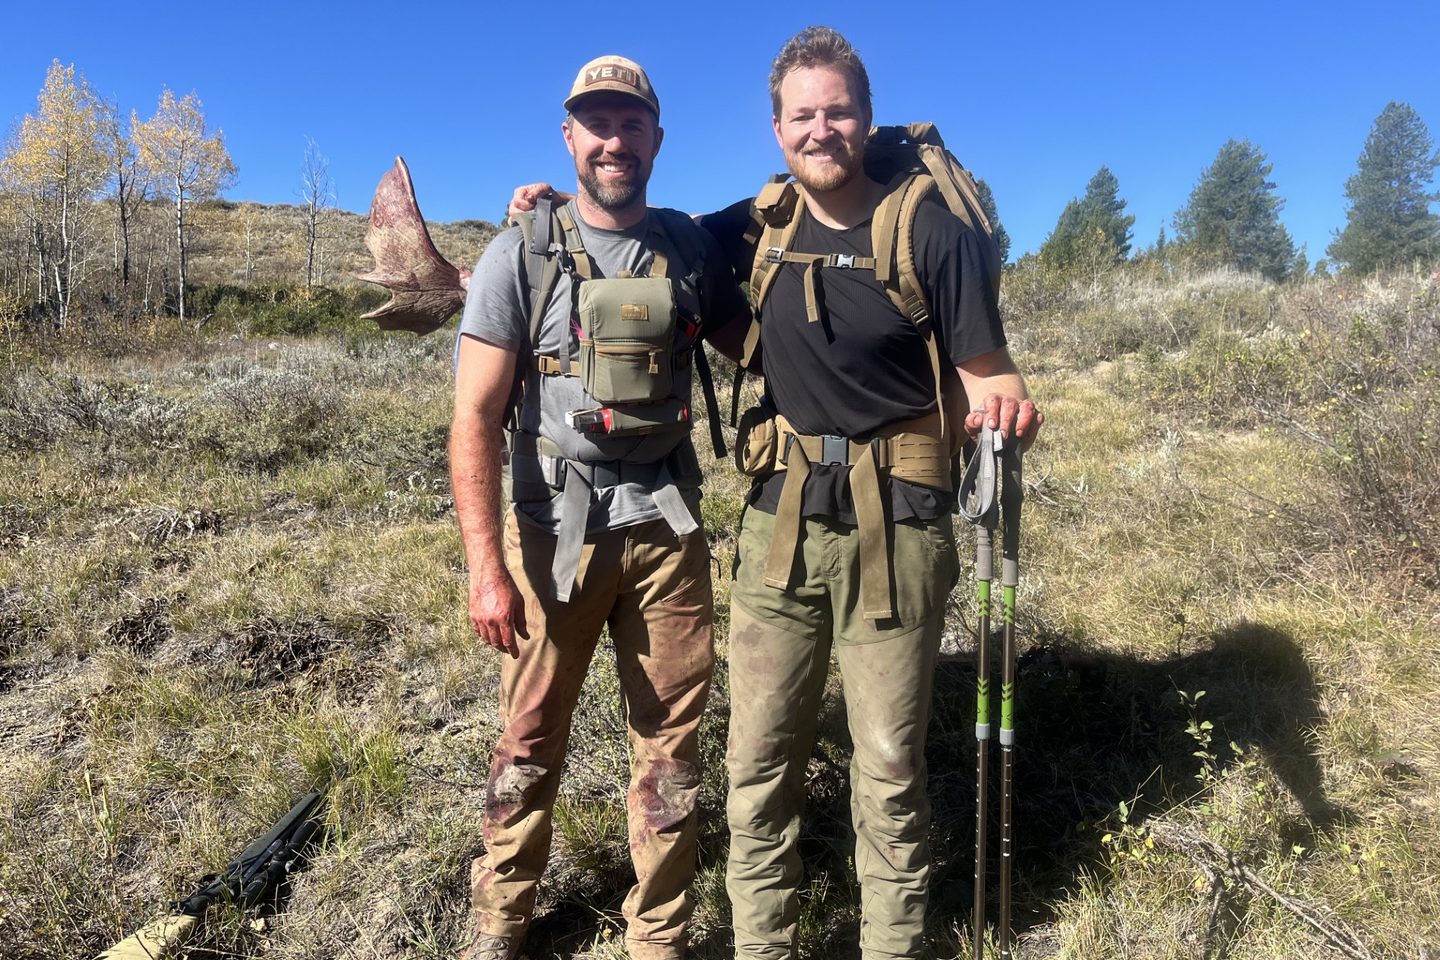
Brian was lucky enough to draw a moose tag in his home state of Idaho this year. This is a once-in-a-lifetime tag in Idaho with a 2% chance of drawing. Amazingly enough, our client and long-time friend also drew the same tag. They hunted for ten days over the end of September/beginning October and both were able to bring home a moose. Multiple friends, including Wim, came throughout the week to help with the hunt and the pack outs. It was a memorable hunt and it's good to have the freezers stocked with wild moose meat.
Get in touch
If something in this issue raised a question on a specific deal, the fastest way to reach us is direct email — Wim at wroach@centennialmortgage.com or Brian at blorenz@centennialmortgage.com. Always send a note through the contact form at roachlorenz.com if that's easiest.
All the best to you and yours as we move toward year end.